Freedom24 gives investors access to international shares, ETFs, bonds and derivatives through a multi-currency account. For UK tax residents, however, it is a foreign brokerage account rather than a UK platform offering a Stocks & Shares ISA.
Its former UK temporary permission has been cancelled and Freedom Finance Europe now operates in supervised run-off, so this guide is intended for existing Freedom24 holders who are UK tax resident.
We explain what needs reporting, which Freedom24 file to download and how to import the complete history into Finbooks to calculate Self Assessment-ready figures.
What you need to know for 2025/26
Freedom24 does not provide a UK Stocks & Shares ISA, so taxable gains and income cannot be excluded simply because the investments remain on the platform.
Shares, ETFs, dividends, bond coupons, interest and derivatives do not all follow the same route through Self Assessment.
The broker’s profit is not a UK tax figure: each relevant transaction must be converted into pounds and HMRC’s share-matching rules apply across brokers.
Finbooks needs the Freedom24 Broker Report in XLSX format, covering the complete available account history rather than only 2025/26.
Do you need to report Freedom24 to HMRC?
You may need to report Freedom24 when you sell or otherwise dispose of an investment, receive dividends or interest, or want to claim an allowable loss while UK tax resident.
Selling shares, ETFs, bonds or other securities can create a capital gain or loss. Dividends, bond coupons and interest are income rather than capital gains, so they have separate allowances and reporting routes. The fact that Freedom24 is based outside the UK does not remove the UK liability: UK residents are generally taxed on worldwide income and gains, subject to their circumstances and any applicable residence rules.
Buying an investment and continuing to hold it does not normally create a reportable disposal by itself. Reporting usually becomes relevant when ownership ends or changes, income is credited or a loss needs to be preserved for use against gains.
Freedom24 does not provide a UK Stocks & Shares ISA
Gains and income arising in the account cannot be left out of Self Assessment on the basis that the investments remain on the platform. For 2025/26, the Capital Gains Tax annual exempt amount is £3,000; SA108 may still be required when total disposal proceeds exceed £50,000 and you are already within Self Assessment.
Can UK residents open or keep a Freedom24 account?
Freedom Finance Europe previously operated in the UK under the post-Brexit Temporary Permissions Regime. Its temporary permission was later cancelled and the company entered the supervised run-off regime.
Supervised run-off allows an EEA firm to service pre-existing UK contracts while it conducts an orderly exit. The FCA states that firms in this regime must not deal with new UK clients and have not received full UK authorisation from the FCA or PRA.
Supervised run-off does not mean every existing account must be closed
You may hold a legacy account that the firm is permitted to service, or you may have opened it in another eligible country before becoming UK resident. Check the entity and current account status shown in your agreement and on the FCA Register.
Tax residence and account eligibility are separate questions. If you are UK tax resident and still hold a Freedom24 account, the UK tax rules can apply even though the broker is regulated in Cyprus and the account was opened abroad.
How is Freedom24 regulated and are investments protected?
Freedom24's European brokerage service is operated by Freedom Finance Europe Ltd and regulated by CySEC under Cyprus Investment Firm licence 275/15. It is not a UK-authorised broker offering new accounts under a standard FCA permission.
Freedom24 states that client assets and money are kept separate from the firm's own assets. Eligible clients may also have access to the Cyprus Investor Compensation Fund if the firm fails and cannot return covered assets or money. The maximum compensation is €20,000 per eligible client in total, subject to the fund's conditions and exclusions.
This is not £85,000 of FSCS investment protection
Investor compensation does not cover market losses and has no bearing on whether the account is taxable. Existing customers should check the entity named in their agreement and the protection attached to that account.
How are Freedom24 investments taxed in the UK?
Freedom24 can place several types of return in the same account, but they do not all belong in the same part of a UK tax return. Separating them first makes both the calculation and the eventual Self Assessment easier to follow.
| Freedom24 activity | Typical UK tax treatment | Usual reporting route |
|---|---|---|
| Shares | Capital gain or allowable loss on disposal, calculated in GBP under HMRC’s matching rules. | SA108 when reporting is required. |
| ETFs | Capital treatment may depend on UK reporting-fund status; non-reporting funds can produce offshore income gains. | SA108 or the relevant income pages. |
| UK dividends | Dividend income, kept separate from capital gains and losses. | Dividend section of SA100. |
| Foreign dividends | Reported gross before withholding tax, with Foreign Tax Credit Relief considered separately. | Usually SA106. |
| Bond coupons and cash interest | Savings or foreign income rather than capital gains. | SA100 or SA106, as applicable. |
| Options, futures and structured products | Capital treatment is common for individual investors, but the contract and pattern of activity can change the result. | SA108 or the relevant income pages. |
The table gives you the reporting route; the calculation still depends on the instrument and the underlying transactions. The same Freedom24 report can contain capital disposals, dividend income, savings income, foreign income and contracts requiring separate analysis.
Shares, ETFs and HMRC matching rules
Selling shares or ETFs can produce a capital gain or an allowable loss. Reportable disposals and gains normally go on the SA108 capital gains summary.
For shares of the same class, HMRC does not simply pair each sale with the purchase selected in the Freedom24 interface. Disposals are matched first with acquisitions made on the same day, then with acquisitions made during the following 30 days. Any remaining quantity is matched with the average cost in the Section 104 pool.
That pool covers the same holding across all your taxable accounts. A Freedom24 sale can therefore depend on a purchase made through Interactive Brokers, Trading 212, eToro or another platform, which is why calculating each broker in isolation can produce the wrong gain.
Dividends and foreign withholding tax
Dividends remain income when they are reinvested automatically or left as cash in the brokerage account. UK dividends normally go in the dividends section of SA100, while foreign dividends usually belong on SA106.
Freedom24 may show the amount received after foreign withholding tax. Your UK return generally begins with the gross dividend before withholding, with any available Foreign Tax Credit Relief considered separately. For 2025/26, the dividend allowance is £500; amounts above it are taxed at the rate applying to your Income Tax band.
Bonds, coupons and cash interest
Bond coupons and interest credited on cash are generally savings income rather than capital gains. Foreign interest usually needs to be included on SA106, while some UK interest can be reported through the relevant section of SA100.
The Personal Savings Allowance for 2025/26 is normally £1,000 for basic-rate taxpayers, £500 for higher-rate taxpayers and nil for additional-rate taxpayers. Selling a bond may create a capital gain or loss, although accrued income rules, deeply discounted securities and the instrument’s legal terms can alter the result.
Options, futures and structured products
Options, futures and structured products need contract-specific analysis. A transaction may be taxed under Capital Gains Tax, but exercise, expiry, cash settlement and the nature of the instrument can change both the timing and the calculation.
For many individuals investing on their own account, derivative gains and losses are capital. Activity that genuinely amounts to a financial trade may instead fall within Income Tax, but frequency or leverage alone does not decide the question. The purpose, organisation, financing and overall pattern of activity all matter.
Offshore ETFs and reporting fund status
An overseas ETF's UK reporting fund status can materially change the tax result outside an ISA. Gains on a non-reporting offshore fund may be taxed as income rather than as capital gains. A reporting fund can also create excess reportable income even when no cash distribution appears in the Freedom24 account.
Check the exact fund and share class against HMRC's reporting funds list. Availability through an EU-regulated broker does not confirm UK reporting fund status.
Check the exact fund and share class
Availability through an EU-regulated broker does not confirm UK reporting-fund status. Check the specific holding against HMRC’s reporting funds list rather than relying on the ticker or fund name.
Why is Freedom24's profit different from your taxable gain?
Freedom24 reports portfolio performance in the account's trading currencies. HMRC requires taxable amounts to be calculated in pounds for the dates on which the relevant transactions occurred.
The purchase cost and sale proceeds of a foreign investment must therefore be converted separately into sterling. Converting only the final dollar or euro profit at the sale-date exchange rate can produce the wrong answer. Exchange-rate movements may create a sterling gain even when the investment barely changed in its local currency, or reduce a gain that appears larger on the platform.
The broker also cannot account for shares of the same class held elsewhere. HMRC’s same-day, 30-day and Section 104 rules apply across brokers, whereas Freedom24 only sees the activity recorded in its own account.
One portfolio figure can contain several tax categories
Dividends, bond coupons and cash interest cannot be netted into share gains, while capital losses cannot reduce dividend or savings income. Foreign withholding tax, dealing fees and derivative cash flows must also be assigned to the correct transaction and tax category.
Foreign currency held independently in the account may require a separate review. Currency other than sterling is generally an asset for Capital Gains Tax purposes, although exemptions can apply to qualifying foreign-currency bank accounts and the treatment depends on how the balance was held and used.
What Freedom24 file do you need for Finbooks?
Finbooks needs the Freedom24 Broker Report in XLSX format. Generate it for the complete available account history so it includes the transactions and cash movements needed to reconstruct purchases, disposals, dividends, interest, fees and currency activity.
The first import should not be limited to 6 April 2025 through 5 April 2026. A share sold during 2025/26 may have been bought years earlier, and that acquisition still contributes to its Section 104 pool. Starting with the full history also helps preserve transfers and corporate actions that affect the cost basis.
You do not need to assemble separate screenshots or manually copy the Trades tab into a spreadsheet. The XLSX Broker Report is the central import file. If the platform cannot produce the entire account history in one report, create consecutive reports with no gaps and upload them together.
How to import Freedom24 into Finbooks
- 1
Log in to Freedom24 on the web platform;
- 2
open Member Area, then select Brokerage Reports;
- 3
choose Broker Report;
- 4
set the reporting period from the first activity in the account through to today;
- 5
select XLS and create the report;
- 6
download the completed file, then upload it to Finbooks by creating a Freedom24 connection or updating an existing one.
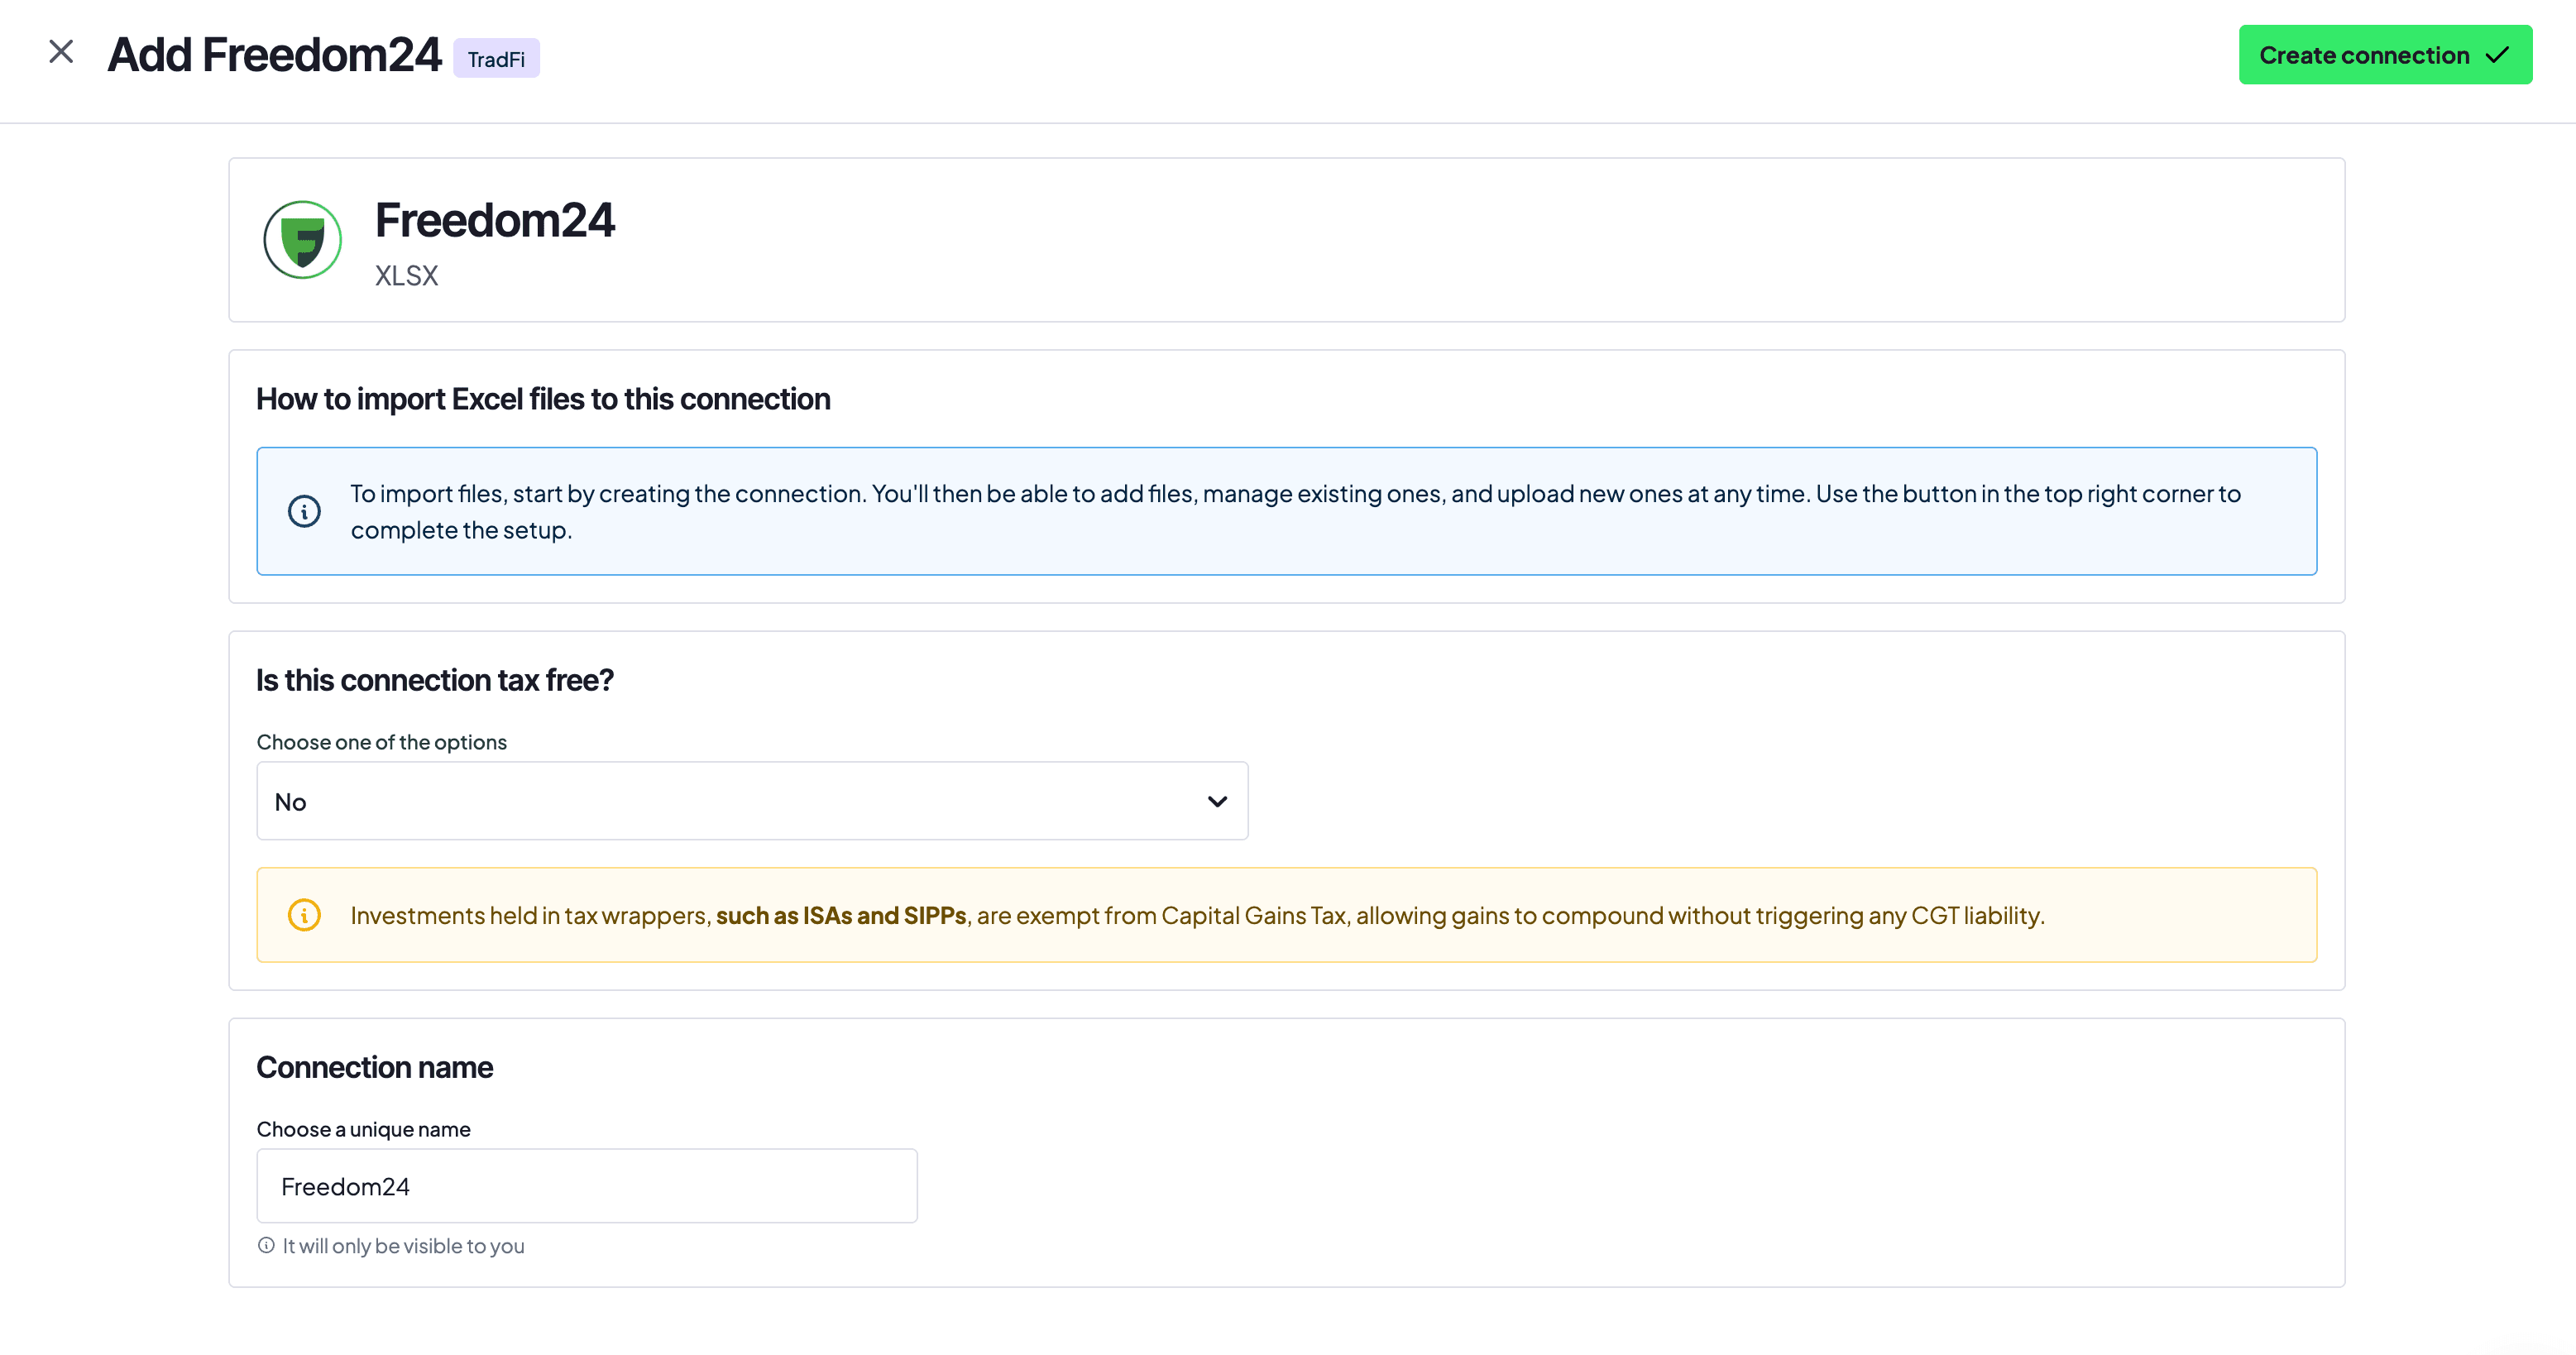
On mobile, the report area is under Menu → Reports and documents → Brokerage Reports. The mobile interface may offer fewer report types, so use the standard Broker Report rather than relying on the visible trading-history summary.
Finbooks reads the imported history, converts the relevant foreign-currency amounts into pounds, keeps income separate from capital gains and applies the UK share-matching rules before preparing figures for a pre-filled Self Assessment.
When is Freedom24 tax due for 2025/26?
The 2025/26 tax year ran from 6 April 2025 to 5 April 2026. The online Self Assessment return and any outstanding tax are normally due by 31 January 2027.
If you need to file for the first time, you generally need to tell HMRC by 5 October 2026. A paper return is normally due by 31 October 2026. Payments on account may also apply to some Income Tax liabilities, with instalments due on 31 January and 31 July.
Generate the Freedom24 report early enough to check older purchase costs, foreign withholding tax and matching transactions held with other brokers. A missing acquisition or dividend cannot always be resolved from the year-end portfolio value.
Freedom24 and HMRC compliance checks
Freedom24 is a foreign broker, but a foreign account is not outside HMRC's reach. The UK participates in international exchange arrangements for financial-account information, and HMRC can also request records when checking a return.
The Broker Report is evidence of what happened in the Freedom24 account; it is not a completed UK tax calculation. Common errors include reporting the platform's net profit, converting a final euro or dollar result only once, omitting foreign dividends and ignoring matching purchases made through another broker.
Keep the original XLSX reports, evidence of transfers and the calculation supporting the return. The final gain or income total should be traceable back to dated transactions, sterling values and the correct Self Assessment category.
Report Freedom24 with Finbooks
Freedom24 makes global markets accessible through one account, but that convenience creates a tax record containing several currencies, asset types and kinds of return. The number shown as portfolio profit does not separate taxable disposals from dividends, interest or open positions, and it cannot apply UK pooling across the rest of your portfolio.
Finbooks turns the Freedom24 XLSX report into a consistent UK tax record. It converts transactions into pounds, applies HMRC's matching rules and keeps capital gains separate from foreign dividends and interest before preparing the figures for Self Assessment.
That becomes especially useful when Freedom24 is only one of several platforms. Bringing every broker into the same calculation allows a sale in one account to be matched with the correct purchases elsewhere, instead of treating each statement as a separate tax position.
You can review the imported history, resolve any missing data and move from a foreign brokerage report to a pre-filled Self Assessment without rebuilding every trade, dividend and exchange-rate conversion by hand.
Try Finbooks free for 7 days and turn your Freedom24 history into Self Assessment-ready figures.
Freedom24 UK tax questions
No. Freedom24 does not provide a UK Stocks & Shares ISA, so taxable disposals and income may need to be included in your Self Assessment.
Some pre-existing accounts may continue to be serviced during supervised run-off. Check your agreement and current account status; the regime does not permit the firm to take on new UK clients.
Download the Broker Report in XLSX format for the complete available account history. If one report cannot cover the full period, upload consecutive files without gaps.